rss
email
twitter
facebook
Showing posts with label Market Commentary. Show all posts

Friday, April 1, 2011

End Month Performance of March (21st to 31st) - April 1st 2011

Traded the fourth week of March but not the last.


4th Week Performance -  March 21th - March 25, 2011

  • Open Week - Long GBP/USD @ 1.6233 from last end week - Closed @ 1.63077 - March 21, 2011
  • Open Week - Long WTI @ 102.28 from last end week - Closed @ 104.97 - March 22, 2011


WTIGBP/USDTotal CentsTotal Pips
+269 cents+74 pip+269 Cents74 pips


This was the performance from within the week though both these positions were initiated from two weeks ago and were unrealized gains.

The overall realized P&L:


WTIGBP/USDTotal CentsTotal Pips
+27 cents+198.7 pip+27 Cents198.7 pips


  • As you see from the realized P&L my second crude trade for the month was timed extremely poorly. For about a week and a half WTI was in down trend for about 2 ATRs. I sat through 2 ATRs of uncomfortable volatility. The proper risk management would have been to set stop loss at 1 ATR reassess on the third week then sat through another 1 ATR of downside volatility and setting it wide enough to be able to catch the recovery that we saw end month. That strategy would have garnered at least 300 - 400 cents vs the 27 cents I realized.  In the end though I'm glad I stuck to my views and convictions of seeing the 105 squeeze I was looking for. The move going into April is another story on its own for another day to tell...
  • GPB/USD trade was overall a very solid trade. I caught about 66% of the move up to about 1.64. I bailed early because I was going out of town and didn't want to manage my position when I was away. Also, wasn't sure how the UK inflation report was going to turn out. Even If I stuck through the inflation report which would have been about 100 pips more, the reversal was hard and fast and probably difficult to time. If anything I would have resulted in the same realized P&L. I sat through about Daily volatility of 100 pips or so before the move took off. 1 ATR risk management would have been sufficient but I was using broad 1.60 base support. 


So my total trades for the month of March realized P&L:

Total CentsTotal Pips
+981 cents+32 pip


Majority of cents come from crude exposure on front month trades (Brent, WTI) and with one week trading the dollar index.

The reason why the pips are so low was because of my poor poor poor NZD trade. Talk about bad timing. Fundamentally I was right but was trying to fight the crowd. In the end the move I wanted came and again came much faster than I expected. The pound was an excellent trade and had I de-leveraged a bit on my NZD trade the pip significants would have been greater. Either way 32 pips is better than negative pips.

Overall a very good positive month thanks to energy trades. My second trade was almost a disaster but I stuck it through. Better risk management would have improved P&L significantly. Got to stick to the discipline...


Analyze Capital LLC
AnalyzeCapital(at)gmail.com 


Tuesday, November 16, 2010

The Three Wise Men


Yesterday was 13-F day in Hedge Fund land. Thus, average speculators (us included) got to peep the holdings of our more well endowed/experienced competitors. Specifically, we now know who owns what. There were no real surprises. So without further adieu let's dive in...

Buffet


We believe that according the name 'investors' to institutions that trade actively is like calling someone who repeatedly engages in one-night stands a 'romantic.'

We surmise Mr. Buffet aimed this quote at those investment banks (Goldman ahem) whose P&L fluctuate due to a voltile revenue stream based on FICC trading.   Mr. Buffet is a man of his word and went hunting for steady revenue streams. Hence, he purchased 1.99 million Bank of NY Mellon shares. BK is a well diversified Financial Services conglomerate and does not rely on investment banking as a main stream of income. In addition, Mr. Buffet upped his stake in WFC by 16.5 million shares bringing his total to 336.4 Million. He increased his stake in Well Fargo four out of the last seven fiscal quarters. We believe Mr. Buffet is betting on WFC's traditional savings and loan franchise, borrow at 0 current rates and lend at higher rates. Meanwhile, he still holds Goldman's feet to the fire with those warrants he purchase at $125/share during the heart of the crisis.

Finally, Berkshire increased their cash position by 23% to $34.5B from $28.05 B last quarter. Mr. Buffet eliminated his stake in Home Depot, reduced his stake in Nike by 52%, and and sold nearly his entire Comcast stake, 12 million shares. Thus, Berkshire Hathaway's equity sales outpaced purchases by $1.2 billion. Let profits run and cut the losers!

Soros


An open society is a society which allows its members the greatest possible degree of freedom in pursuing their interests compatible with the interests of others.

Indeed it is. Mr. Soros exercised his right to pursue interests compatible with others in that he took some profits and diversified his Gold positions. Soros Fund Management Sold approximately 550,000 GLD shares last quarter and now hold a cool 4.7 million. This is significant in that the Soros' holdings are down from 1.5 Million GLD shares under management from the peak in December of 2009 when 6.2 million shares were held.  As we noted in our last post, the gold trade is a crowded one and the GLD is the most popular vehicle. In lieu, Mr. Soros diversified his holdings and purchased 5 million shares of The BlackRock managed iShares Gold Trust (IAU). Again, no surprises here. If we recall correctly, Soros called Gold the ultimate bubble not too long ago. Suffice it to say he still feels this way.


John Paulson


There is a chance – a very good chance – that gold will be the next NASDAQ.

Mr. Paulson shows some hubris. To our delight he puts his money where his mouth is. Paulson & CO. maintained 31.5 million shares of the SPDR GLD ETF, approximately 7.4% of the entire float, last quarter. Essentially, he must think $1500 Gold will come sooner than later. Also, Mr. Paulson was a heavy seller of financial equities. Paulson & Co. sold 1.1 million GS shares, 82.7 million C shares, 2 million JPM shares, 2 million WFC shares, and 30 million BAC shares. For what its worth, this may explain negative HF bias towards the XLF last quarter and go a long way into explaining why financials did not participate in the September/October equity rally. Though we are not conspiracy theorists here, just backward guessing speculators.

Comments


Even though we did not rigorously detail the nuances of each manager's portfolio, the major changes were noted. What do we think? Safety and profit taking were the prominent themes. Soros ensured he has more liquidity in case Gold dips. Buffet took the consumer-related risk out of his portfolio. Paulson reallocated capital and took money off the table a la profits and losses in financials. Why are these men wise? All three stuck to their principle investing thesis. In times of turbulence many of us question our positions, logic, rationale, and sanity. However, it is times like these in which we can also become wise men and clarify our unique trading styles.

-Patrick M. Ambrus

Sources: bloomberg.com, cnbc.com, ft.com, thelordoftrading.com

Thursday, November 4, 2010

A Central Banker's Cocktail Party: Tequila or Water?


What is Quantitative Easing? A government monetary policy occasionally used to increase the money supply by buying government securities or other securities from the market. Quantitative easing increases the money supply by flooding financial institutions with capital in an effort to promote increased lending and liquidity.

Now that's out of the way we can dissect the size, announcement, and long-term affects of the easing on the Global Financial System.

First let us say congratulations to the United States Federal Reserve, in eight months time you will maintain a $3 Trillion balance sheet. The Central Bank is now the largest Hedge Fund in the World. Kudos, no really. Let's take a few moments to put this number into perspective. In, 2009 the U.S. GDP was $14.25630 Trillion. The IMF forecasts growth in 2010 of 2.6%. A back of the envelope calculation puts 2010 output at 14.627. Thus, in June 2011 the Federal Reserve will control assets worth 20-21% of 2010 Gross Domestic Product. In 2007, The Fed's Balance sheet was worth only 6.4% of Gross Domestic Product. All we can say is Kudos.

Consequently, the NY Federal Reserve has a tall glass to fill:

The FOMC directed the Open Market Trading Desk (the Desk) at the Federal Reserve Bank of New York to purchase an additional $600 billion of longer- term Treasury securities...Taken together, the Desk anticipates conducting $850 to $900 billion of purchases of longer-term Treasury securities through the end of the second quarter 2011.

I expect on-campus recruiting to increase at the next NYU career fair. Anyone want to take the opposite side of this trade?

Looking Back,today's market action after the FOMC announcement was incredibly entertaining. We observed The S&P 500 oscillate down to 1183 and then rocket back to 1199 to close the session. The EUR/USD fluctuated 190 pips, a range that would make any Black Box trader proud. Gold dropped from 1348 to 1327 and now trades at 1355. Ironically, Natural Gas was unchanged throughout. The fourth of July came late this year, hope you did not miss it!

SPX

Dollar Index

Moving forward, Quantitative Easing will surely inflate Global Asset Markets. Will it? Regardless, this is the current thesis the Fed operates with. The goal of 'QE II' is to re-inflate the U.S. economy. Specifically, the Federal Reserve desires an asset re-allocation trade. The FOMC hopes to push investors out of 'safe-haven' Government Debt instruments and squeeze them into more risky asset classes such as equites, commodities, junk-bonds, and real-estate. Why would the fed want to turn the proverbial risk switch off? Don't jump to conclusions, keep reading!

The second leg of this trade hinges on the 'wealth effect', The premise that when the value of stock portfolios rise due to escalating stock prices, investors feel more comfortable and secure about their wealth, causing them to spend more . Miller Tabak estimates this effect will carry a multiplier of 3x. Hence, the $600 B of Quantitative Easing will create new consumer wealth of $1.8 Billion. The Fed supposes a multiplier of this magnitude will allow consumers to feel comfortable parting with their hard earned Dollars and spend without discretion. Therefore the economy will grow, inflation will rise, unemployment will fall, and The 'Red, White, & Blue' will flourish in economic and financial prosperity once again.

Personal Savings Rate

Even Though The FOMC's policy makers and economists are a collective of the smartest and brightest in the United States of America, Quantitative Easing II sounds too good to be true. Why you ask? First, any good trader knows timing the market is nearly impossible. Second, who is to say consumers will look at their 401k statements, feel wealthier, and decide to spend. Lastly, 'QE II'has never been done before. The original U.S. Quantitative Easing was executed during the heart of the credit crisis. The impetus for the current version is plainly different. Also, Japan's attempts fell flat and failed miserably. In short, we are critical here because we are uncertain of the outcome. The Fed should be too.

To clarify we will attempt to explain our thoughts in a simple thought experiment:

Suppose you are two hours late to a cocktail party. There is food, drinks, and irresponsible adults galore. You head to the bar for your first drink of the night. The bar tender informs you the only beverages still available are water and tequila. At the same time you approach the bar an irresponsible adult, who consumed five beverages prior to your arrival, also approaches. You think, I hate tequila because it makes me sick. Instead you decide to drink water and enjoy the experience without alcohol. Meanwhile, the irresponsible adult orders another drink. Mind you this is his 6th drink and first of tequila. You think, 'I wish I was indulged in his level of intoxication'. Though, your next thought is 'I am so happy I am not that guy, he won't be able to get out of bed tomorrow'.

Is the Fed an irresponsible adult or a water drinker? Take from this simple thought experiment what you will.

Undoubtedly, we are entering uncharted territory. Here's to watching and waiting for events to unfold. Hey, if you get bored check the BOE decision at 08:00 EST and the ECB decision 45 minutes later. Surely the ECB won't surprise!

Cheers,

--Patrick M. Ambrus

Sources: Investopedia.com, The Gartman Letter, FederalReserve.gov, NewYorkFed.org, BEA.gov

Disclosure: We are Long the GBP and short the USD.

Friday, October 15, 2010

Early Bird Update


00:016- Equity Commentary

The Nikkei 225 is off .52% to 9530. Bloomberg attributes the drop to Investor Sentiment:

‘“Investor sentiment is a bit twitchy,” said Shane Oliver, Sydney-based head of investment strategy at AMP Capital Investors Ltd., which manages $85 billion. “The U.S. data was a bit poor. This week we’ve had a couple of good days and investors may be looking to take profits.”

The CSI is up 2.00% or 65 points to 3,288.52. The ASX 200 is down 13 points to 4686.60.

In the U.S. GE reports before the opening bell on the NYSE: “Analysts project a second straight quarter of higher profit after eight periods in which it declined or was little changed. Adjusted earnings may be 27 cents a share on sales of $37.4 billion, the average of estimates in a Bloomberg survey.”


SPX, Dow, and Nasdaq Futures are flat. 5 and 10 Year Treasury futures are up 0.05% as of writing.

00:05- Commodity Commentary

Energy- Nat Gas is currently positive by $0.0001, up on light volume. November CL contracts have followed the dollar for most of the session. Losses were paired from 82.53. November contracts are up at $82.75/barell.

Precious Metals- Silver has led the rally and is up 1.47% or $0.36 to 24.795. I see $25.00 on Silver before $1400 on Gold. Gold is positive on the session up $3.60 to 1381.30.


Grains- Wheat and Corn continue to rally as we have a global shortage. In addition corn may be benefiting from E15 legislation now in place. Though, bullish activity is in order until the next USDA report reports accurate Supply numbers. The always important yield/acreage ratios remain on the low side when measured against previous estimates. Wheat is up .82% and Corn is up .93% on the session. Additionally, Soybeans continue to extend gains, advancing by 1.20%.

00:00- FX Comentary

EUR/USD- the pair traded down as low as 1.4009 at 20:15. The pair then traded up to 1.4049 and faced resistance at 1.4050. The 'Sovereign Default Trade' seems to have found support in the 1.4025-1.4035 range. Currently we are long at 1.40387.


Cable trade - The pound traded down to 1.5985 at 20:30 and has since traded up around 1.6005. The pair sits at 1.5997 at present time.


U.S. Dollar Index- The DXY gained traction and is trading up to 76.88.

U. S. Trading

CPI , Empire State, and Retail Sales come in at 08:30.  I expect 'robust' retail sales data to bolster equities.  Additionally,  expect a weaker USD tomorrow with stronger Commodities.  Good morning and good luck.

-Patrick M. Ambrus

Sources: Bloomberg.com, Stockcharts.com, The Gartman Letter, Financial Times

Thursday, October 14, 2010

Lost in Transition


As the memories of summer dawn upon us and autumn's head-winds transition us into colder months, we remain stuck in a period of cryptic transition.  The green leaves are slow to transform into  red, yellow, and orange decay.  Throughout September and early October, temperatures here on the Eastern United States remain elevated with splashes of summer, spring, and autumn surprising us on a daily basis.  I seek clarity in these matters.   Moreover, when will a new forceful trend form and carry us into colder, cooler, and darker days?

This same phenomena can be easily applied to current market conditions.  We are at a a cliff looking over the edge and waiting to be pushed by "someone or something."  For the past month of trading the impetus for asset price appreciation came at the behest of the U.S. Federal Reserve.  Mr. Bernanke made it clear at the Fed's anual Jackson Hole Summit:

Notably, since December 2008, the FOMC has held its target for the federal funds rate in a range of 0 to 25 basis points. Moreover, since March 2009, the Committee has consistently stated its expectation that economic conditions are likely to warrant exceptionally low policy rates for an extended period. Partially in response to FOMC communications, futures markets quotes suggest that investors are not anticipating significant policy tightening by the Federal Reserve for quite some time. Market expectations for continued accommodative policy have in turn helped reduce interest rates on a range of short- and medium-term financial instruments to quite low levels, indeed not far above the zero lower bound on nominal interest rates in many cases....


In support of the stock view, the cessation of the Federal Reserve's purchases of agency securities at the end of the first quarter of this year seems to have had only negligible effects on longer-term rates and spreads. 

Many Market participants took statements like these as indicative of greater 'Quantitative Easing' measures in the near-term with an emphasis placed on purchases of longer-term maturing Debt instruments.  Thus, the cruise ship 'QE2' set sail and every trader, analyst, investment banker, and speculator jumped aboard.  The rumors of 'QE2' allowed an appreciation  of equity prices, commodity prices, and a continued rally in the bond market.  However, many market participants fight a potentially painful hangover as they wait for another round of cocktails to tide them over.  Until 'QE2' becomes a reality, the current run-up in asset prices will continue to be predicated on rumors supported by ubiquitous supply & demand, fundamental, and sentimental data.

Consequently, The USD has taken the brunt of the pain over the past month of trading.  The US Dollar Index is down 6.8% in the period from September 1st -October 11.  Even though this downward trend has been in place since early June, the recent rumor mongering has certainly contributed to the Greenback's precipitous plunge in value.


EUR/USD has appreciated by 9% since September 1st.


OK so what, why does a weak dollar matter? As the emerging markets transition into developed economies won't the USD need to allow the wealth to spread to other currencies, 'new reserve currencies'?  In the future, the USD may no longer be the benchmark for which emerging market rates are pegged or for which all central bank reserves pile into.  However, these structural changes will not placate current financial psychology for some years time.  Hence, we must look at the short-term trends to discern directionality.  Disregard, financial profits, journalists, and fund managers who say otherwise.  Trade the trends.  Block out the noise.


-Patrick M. Ambrus

Sources: Stockcharts.com, Federalreserve.gov

Thursday, October 7, 2010

Quiet Before the Strom


Interest Rate Day 2 will reign central banking policy among us in less then 4.5 hours.  The first such decision emanate from the Bank of England at 7:00 EST.   Jean-Claude Trichet's ECB is on deck and will step to the plate 45 minutes later.  In the mean time, let us examine the potential ramifications that hinge on the tongues of the notorious 'Lords of Finance.'

Is there any any legitimate doubt the ECB will keep rates in check? No doubt here.  I volunteer to take the opposite side of that trade.  Maybe Mr. Kerviel will humor me.  The issue in question more or less is whether or not Mr. Trichet will touch on the bleek Irish banking system, lack of deposits held by Spain's Cajas, Greek austerity, or effects of a stronger Euro on medium-term growth.

The ECB statement will most likely sidestep Ireland's dire banking sector and potential liquidity problems in Spanish financial institutions.  ECB rhetoric on the aforementioned issues will trickel out in various policy speeches and interviews.  Now let us savor the meet and potatoes.  Surely, we can assume the words 'growth' and 'inflation' are seared throughout the policy statement.  The 'Lord' will reaffirm that the European economic recovery continues on the forecasted track bolstered by 'robust' (there's that word again) economies (Germny, ahem).  Next, Trichet will unwrap the 'PIIGS' with hyperbole that includes restructuring, budget rebalancing, and structural change.  Lastly, the spotlight will surround inflation.  I surmise The ECB will not attribute lack of inflation to a stronger Euro but rather pent up demand.  At this point the Germans will be thrown praise for their growth through domestic demand.

All of this banter is pure speculation.  However, what I attempt to underline is the ECB's 'poker face'.  Time and again the ECB protects the Euro-Zone through tight-lips.  When Lip-service is provided the market bites.  Let us recall how long it took Wall Street to buy a coordinated bailout between The Fed and U.S. Treasury.  The ECB/IMF bailout of sovereigns slowed the bleeding immediately.  What am I getting at?  The ECB can move markets just as fast if not faster as than the next central bank.


May 6 - July 6, EUR/USD rate rebounded in 2 months


On a more speculative thought, I am intrigued to see the Dollar Index touching 'Armageddon Support'.  Could Non-farm Payrolls provide the impetus for a rigorous dollar rally?  I expect to see 76 on the above index before a bottom becomes apparent.  Though, I will keep the 'Armageddon Support' in mind over the next few trading sessions regardless of Quantitative Easing round 2.  At present, $ 1 Trillion seems to already be priced in.  

This next  chart  is of the Dollar Index.  Here I look for 'highs' as a an indicator of risk aversion or more simply put, a fear gauge.


What will come of Rate Day 2?  I am not a forecaster, only a lowly speculator.  However If I were a betting man I would put my faith in the Euro currency for the next few sessions.  Good luck trading!

-Patrick M. Ambrus

Sources: Stockcharts.com, federalreserve.gov, Financial Times, Bloomberg.com, starmedia.com

Tuesday, October 5, 2010

Rates Down Under

The AUD/USD pair corrosively sold off the moment the rate decision became apparent at 11:30 EST. The pair rallied more than 150 pips since the initial sell-off and now trades higher around 0.972o. Unfortunately, I was on the wrong side of this trade. Lesson learned.


Interest rate day came and went.  The RBA decided not to raise rates by the sure-fire economist/analyst prediction of 25 basis points.  Instead, rates stayed in check at 4.50%.  Central Bank Governor Glenn Stevens explained:

“Financial markets are still characterized by a degree of uncertainty, and are responding both to differences in growth outlooks between regions and evident strains on public finances and banking systems in several smaller countries in Europe. Most commodity prices have changed little over recent months, and those most important to Australia remain very high.”

The tacit implication here is that while commodity prices continue to rise, notably Copper, the substantial appreciation of the “Aussie” supplants any real threats of inflation in the near-term.  I surmise the central bank employed this policy to assist in job creation through private sector reinvestment, which in turn may help reignite housing demand and retail sales.  In the minutes the RBA suggested higher rates over a mid-term period.  The central bank did note cooling domestic demand and global economic uncertainty as concerns:

“Several measures of inflation expectations had eased a little over recent months to be around average levels. Similarly, business surveys reported that the share of businesses planning to increase their prices over coming months was around average…While policy had to be alert to these risks, members considered that if the central scenario came to pass it was likely that higher interest rates would be required, at some point, to ensure that inflation remained consistent with the medium-term target. For the immediate decision, there had been no significant change in the overall outlook, with conditions looking a little stronger domestically than they had at the previous meeting, but looking a little weaker internationally.”

In addition, I found the IMF’s recent comments in their annual Article IV moderately firmer than those found in the most recent RBA minutes:

“Should the recovery unfold as expected, monetary policy will need to tighten further to contain inflation pressures generated by the mining boom… from a medium-term perspective, our assessment is that the exchange rate is mildly overvalued… This overvaluation is likely to be temporary and may dissipate with the eventual normalization of interest rates in the United States and other advanced economies.”

Here, The IMF argues interest rate policy (tightening) as the correct tool to cool inflation.  Conversely, the RBA seemed content to let the ‘Aussie” appreciate and reap the benefits of cheaper cost of capital and simultaneously increase prices of exported commodities.  Note, as the CNY remains weak against the USD, imports from Australia become more expensive for the People's Republic of China. Either way, inflation will cool. 

What caused economists and analysts to maintain such conviction of an interest rate hike?  The empirical reason may never be discerned.  I maintain a theory though. Many rumors sloshed between investors, traders, and media pundits that the Central Bank Governor openly desired hirer rates. However, Mr. Stevens did not lay his cards on the table in between the release of RBA minutes on September 7th and the rate decision on October 5th.  Thus, many of ‘us’ were fooled.  Next time 'we 'ought to err on the side of caution when attempting to forecast a Central Banker’s policy decision.

--Patrick M. Ambrus

Sources: http://www.rba.gov.au/, bloomberg.com, imf.org

Wednesday, September 29, 2010

Navigating Global Capital Markets


Trading FX is right now is like navigating the Amazon River, 'Grey Swans from Extremistan' lurk around every land mass..... As the often quoted John Maynard Keynes once advised, "The market can stay irrational longer than you can stay solvent."
    Credit Default Swaps on Irish, Portuguese, Greek, and Spanish Debt continue to widen. Anglo Irish debt was downgraded by Moody's on Monday and now needs another lifeline of 5B Euros.  Yet, the Euro continues to strengthen.  Mr. Bernanke and Mr. Obama must be smoking a fine Cuban cigar at the moment because they are the only 2 policy makers of recent memory to weaken their currency without  significant lip service.  The Japanese MOF should take the lesson...start a trade war with China and watch your currency tank...There is much fear in holding US Dollars at the moment.  Mr. Guido Mantega of Brazil is right, we do have a full fledged currency war of devaluation and the U.S. is winning.
      Also of note, Mr. Yu Yongding an advisor to The People's Bank of China spoke in Singapore  of a full fledged dollar crisis, to quote the man, "Such a huge amount of debt is terrible and the situation will be worsening day by day.  I think we are one step nearer to a US Dollar crisis."  Cheers to you too mate.
        This morning AUD is off its highs of .9780 levels seen in Tokyo trading overnight and has pulled back toward .9700 levels.The AUD continues to test new highs as it inches towards parrity with the USD and makes new highs against the JPY.  Though, the latter has internal economic issues of its own which continue to put downward pressure on any of the Yen's major pairs.  The appreciation in large is due to sustained demand for Australian base/industrial metals from China and ASEAN countries in general.  Also, Australia maintains the highest nominal interest rates, currently at 4.5%, of any G20 country and thus is perfect for a reverse carry trade involving the USD.  Ironic how times have changed.  I can remember the days when U.S. assets became the beneficiary of an Asia Pacific carry trade.  And then we had a realestate market collapse in correlation with all other asset classes for that matter....Low rates, continued AUD strength!
          Meanwhile, the only commodities that want to rally are precious metals...Agri commodities crashed like the titantic yesterday and continue to hit icebergs today.   This is possibly due to the recent sanctions China placed on imported U.S. Chickens.  Chickens love grains as a main source of their diets.  Also, the recent run-up in Agri prices does justify a correction if prices are to move higher in the 4th Quarter.  Natural Gas is trading lower and Oil cannot hold on to any incremental gains.  Though API data from last night was somewhat bullish, and DOE data should help prices firm a bit, but their is no support in sight. Nat Gas is suffering from a lack of supply scarcity.  In fact new inventories appear every day and remain above our famous 5 year average range.  Yet, this makes little sense considering storage capacity and new LNG technologies make storage and shipment of the energy easier and cheaper than ever. I will note that Sugar, Cocoa, and Coffee performed well in yesterdays session largely attributed to you guessed it, dollar weakness.
            Bill Gross published a grim outlook in his October outlook letter.  He highlighted Stan Drunkenmiller's retirement as a Harbinger of things to come in the fund management industry.  He argues that the days of double digit returns are over due to a lack of asset inflation, increased regulation, and deregulation.  Indeed these things are all true.  One must take Mr. Gross' comments with a grain of salt as he manages the world's largest bond fund in PIMCO.  His comments do coincide with a 10% workforce reduction at DE Shaw, one the world's largest Hedge Funds with approximately $21 B of assets under management.  HF's are struggling to produce alpha these days.  According to HFN Hedge Fund Aggregate Index funds are up only 0.14% YTD through June 2010.  The FT reports Hedge funds are up 1.45% YTD.  Times are grim when the best managers of money can't make a buck.
              It is understandable that there is an underlying current of fear surrounding the developed markets of the world.  Emerging Markets were thrust into the spotlight during the most morbid of days during the credit crisis and have been in the spotlight since.  OECD economies continued to point to Emerging Market Demand and growth as the way of the future and how this shift is a 'structural' one that will change the way the global markets do business.  All I can say is, not so fast jack.  Without demand for emerging market exports from developed economies there will be no new growth.  Unless of course the ubiquitous Emerging Markets can create a sustainably contempory domestic demand system for domestically produced goods.  I doubt Malaysia needs all those those textiles and garments they continue to churn out.

              Undoubtedly, big corporates still reside in developed markets.  Inventories have refilled after bone dry levels spawned a rampant increase in production over the last 2 quarters.  Thus, unless OECD demand returns to the global marketplace, emerging markets will not be able to maintain their 'robust' growth systems and will inevitably slow down.  Global 'Austerity' is in order.  We should all trade accordingly.

              Patrick M. Ambrus
              Contact: analyzecapital@gmail.com

              Sources: Financial Times, The Gartman Letter, Bloomberg.com, HFN.com, The Black Swan, PIMCO.com

              Monday, September 27, 2010

              Headwinds of Change

              Unpredictable Market Forces at Work


              After a positive week for U.S. equities, market action lacks directional impetus. What will drive equity markets higher? It is clear to us window dressing season is in full effect. Many fund managers and Institutional Investors continue to pile into crowded, growth-oriented, and alpha-seeking equity trades. In addition, many prominent investment bankers sitting in the position of 'Head of Global Equities', at their respective shops, continue to preach 1300 on the SPX by year end. Is this feasible? Sure, but it is not likely.

              Much of the current rally in the SPX from August lows of 1015 has been due to a weaker USD across the board. One can argue the impact of illustrious economic data releases on price swings until blue in the face. Yet, since the fear of debt contagion in the Euro-zone abated panic and worry shifted back on the country with the world's largest Gross Domestic Product. Since then, the EUR, CHF, JPY, and AUD have all made substantial advances against the 'Greendback'.


              Down Under


              Australia continues to benefit from their trade relationships with Asia in that exports of commodities have led to sustainable growth down under. The economy picked up last month creating 29,000 new jobs predominantly in construction and industrial sectors. As long as Chinese demand for iron ore, copper, and aluminum remains consistent, thE AUD Will continue to appreciate against all major pairs.


              Efficiency


              The 'Swissy' benefits predominantly from the risk-on/risk-off trade. The linguistically diverse country maintains a current account surplus of 8.9% of GDP, inflation hovers around 1% while unemployment is below a comfortable 4%, and 2011 GDP growth forecasts 2% growth. If one wants safety what is not to like? In addition FX traders seem poised to test the patience of the SNB again. Recall when the SNB stepped in with 'unilateral intervention' and sold Swiss Francs to keep the rate above 1.30 EUR/CHF. Will they sell Francs and buy Dollars? No, the Japanese already failed in this endeavor.


              Tradition


              The Japanese economy, like the U.S., is struggling to maintain growth. Deflation wanes in the balance and export demand is tailing off in large due to a strong currency and shrinking profit margins at the likes of Sony, Toyota, Bridgestone, and Kobe Steel. With a dire economic situation the MOF stubbornly talks up the JPY and the need for intervention. Though, by 'unilaterally intervening' in the FX markets already traders know the MOF has a gun. The question is how many bullets are in the gun, and does the Ministry possess the courage required to fire a full clip? Time will tell on the latter. I doubt we have seen the last of 'unilateral intervention'. Speculators who place bets in JPY strength will not learn until the MOF reverts back to 2004 tactics and dilutes the market with over $1 Trillion of Yen. Whether or not Kan's $55 B stimulus package helps weaken the JPY remains to be seen.

              Lastly, I would like to touch on the political issues underpinning the currency. Since Ichiro Ozowa was ousted in his most recent attempt to gain power, Naoto Kan appeased the former's supporters with currency intervention. I trust the exporters mentioned above took note of this and will put pressure on Kan's administration to intervene again. Many have made it resolutely clear; 'we want USD/JPY rate at 95'. If Kan wants to keep his job longer than his predecessors he will intervene again and again until the Yen stops strengthening.


              The Little King of Everything


              Alas we have but one more pair to discuss, you guessed it, EUR/USD. As mentioned by Dennis Gartman this morning, 'This was the level from which the EUR plunged earlier this year... it marks almost perfectly the 50% retraetment of the EUR's collapse from the highs of 1.5200 last December to the lows of 1.1900 this spring.' 1.3500 will serve as a hard line of resistance over the next trading session. This morning around 10:00 the pair jumped above this level on a large candle to the upside. However, the pair rocketed back down to the 1.3450 levels within the next hour.

              Also, ECB buying of sovereign debt is slowing. Last week the ECB bought only 134 M EUR of bonds in comparison to 323 M EUR the week prior. Maybe the ECB feels confident the liquidity in the sovereign debt market is here to stay, only until it dries up again. Another important point to note; many Germans are becoming unhappy with the 'Christian-liberal Coalition', noted in the latest edition of the economist. Any political instability surrounding the Euro-zone's growth engine may cause uncertainty in the single currency. However, I should note that this is pure speculation on my part.

              Undoubtedly, the EUR/USD pair is driven by none other than the U.S. FED action. Various traders, analysts, and media alike expect a second round of 'Quantitative Easing' in which the FED once again opens up its balance sheet to buy U.S. Government Debt. Rumors suggest debt purchases of $1-2 Trillion of longer-term U.S. Treasuries. This is nonsense. If the FED wanted to create artificial inflation they already would have done as much. Especially considering the mid-term elections put a choke-hold on any further monetary policy action. I suspect, as a rumor from the WSJ this afternoon put it, 'Rather than announcing massive bond purchases with a finite end, Fed officials are weighing a more open-ended, smaller-scale program that they could adjust as the recovery unfolds.' Cheers. This ought to give the Bond market rally a bit more time run and allow equities to cool after a monster September.


              Impetus for Change

              Now let us examine a few possible harbinger's for a trend reversal in Dollar weakness. On Friday October first Global PMI data will release staring with CHina and ending with U.S. ISM. Last month trader's took China's moderate August reading of 51.7, up .5% from the month prior, as a reason to buy equities. The SPX rallied nearly 3% and closed up more than 30 points on the session. What would have happened if Chinese PMI came in around say 48 or 47? Equities would be in for a sharp and painful sell-off methinks. Hence, the fear of a global slowdown in consumption/demand would shift to the far east and away from the U.S. Perhaps poor EU PMI might just do the trick if the Chinese index posts 'robust' gains. Either way, I expect this data release to be a harbinger of asset allocation in the coming month.


              Trade

              We are gearing up for a switch in sentiment with a 'Strong Dollar Story' leading the charge. Specifically we like the the dollar against the CHF, CAD, and JPY. In addition, we see energy as the place to be in the coming months as seasonality changes. Be cautious though, this type of trading environment is dangerous.


              Patrick M. Ambrus
              Contact: analyzecapital@gmail.com


              Sources: The Economist, The Gartman Letter, Financial Times, FT Alphaville, WSJ.com, bloomberg.com

              Monday, September 20, 2010

              Do Your Own Homework-SPX Update


              'Buying Gold is an excuse for people not to do their homework.'

              -Alex

              SPX: 1 Year Daily Chart:


              Another day another dollar: that is true if you were long the SPX in U.S. trading today. The SPX rallied 1.45% to 1141.92 on the session led by Energy, Consumer Discretionary, and Industrial stocks. Many Tech bellwethers displayed robust performances as Google rallied 3.7% to 508 and AAPL closed above 280 up 2.85%.

              Pop Quiz: Why did equities rally today class?


              a. President Obama's Town Hall assured investors America is "The Greatest Nation"
              b. The SPX broke resistance of 1131
              c. Japanese Markets were closed
              d. The Tea-Party will uproot American Politics
              e. No significant economic data released
              f. I forgot how to take these tests

              The answer is probably a combination of b, c, and e. The S&P finally broke out of its uninspiring trading range on light volume. Though, this may be short lived. Early in the session gold rallied to new highs around 1284. However, these gains were unsustainable. In addition, agricultural commodities, base metals, and Natural Gas led commodities lower. The USD failed to sustain any gains against the Euro, Sterling, 'Aussie', and CHF. Also, the bond market lacked bullish convictions. Alas, capital flowed into equities by default.

              October Nat Gas:1 Month Chart


              December SPX E-mini: 1 Month Chart


              Trades
              We took advantage of the sharp sell-off in December Nat Gas contracts and entered a long position as prices firmed. Also, we are long the Dollar vs. CHF. U.S. Housing Starts come in at 08:30 and The Fed decision is at 14:15 EST. We expect equities to pair some of their gains in tomorrow's session.


              Patrick M. Ambrus
              Twitter: AnalyzeCapital

              Sources: Stockcharts.com, Bloomberg.com, VanityFair

              Monday, September 13, 2010

              Ripe for a Short


              Today the SPX rallied and finished up 1.15% to 1122.29 above the 200 Day Simple Moving Average. The rally was in large part driven by 'robust' Industrial Production and domestic demand data released by China over the weekend. The Energy and Materials sectors led the SPX higher today. WTI Oil was up over 1% on the session to $77.20. Copper and Natural Gas also benefitted from the rally.

              GSCI Commodity Index


              Last night Basel III capital requirements released and were essentially a practical joke on banks. Banks will be required to maintain a Tier 1 Capital ratio of 4.5% (common equity after deductions) and a buffer of 2.0% by 2013. Keep in mind, Lehman had a Tier 1 Capital ratio of 11% when the investment bank imploded. So much for stringent regulation. Needless to say, financials rallied hard on the session.

              SPX 1 Year Daily


              VIX


              Where do equities go from here? 1131 is the next key level of resistance on the SPX. Tomorrow U.S. retail sales release at 08:30 and disappointing numbers could be the impetus to drive equities lower. In addition, we are approaching overbought technical levels on the RSI (62 on the 1 year daily). In addition, the VIX traded down around 21 today. The volatility index is ripe for a pop up to 23 to 24 over the next few sessions. Thus, now may be the time to get get short the SPX.


              Sports: Jets vs. Ravens tonight. Gang Green will be victorious.

              Patrick M. Ambrus
              Twitter: AnalyzeCapital

              Sources: Bloomberg.com, FT Alphaville, TheLordofTrading.com, baseliii-accord.com

              Thursday, September 9, 2010

              Black Gold


              But eventually it's a question of access: Getting access to fields is on top of the oil companies' agenda. We see a substantial build-up of supply occurring over the coming years.

              -Daniel Yergin


              WTI Crude Oil traded higher up to $75.95/barrel during the morning session. However the commodity pulled back when the EIA data was released. The October contract currently trades at $74.10 Below, I compiled some of the key EIA data for your own synthesis & analysis.


              Price Pressure
              Why has CL1 traded in a range for the past month? There is a large contagion gap between the near month October Futures contracts and the November Contracts of 2.04%. As settlement date approaches, November prices will fall. In addition, supply levels in Kuching Oklahoma remain above historical levels for this time of year.

              Macro View
              Growth numbers out of China have been less than stellar. China PMI data was up only .5% from July to 51.7%, HSBC numbers were below 50. Also, the 'Deflation Story' in the U.S. and Japan will not help the perception of commodities. As money continues to flow into the bond market inflationary investments become less attractive. Lastly, there has been less conflict in the Middle East than normal. Thus, OPEC sour-crude supply is not in danger of shortages in the near-term.

              Highlights from EIA Report


              -U.S. crude oil imports averaged 8.9 million barrels per day last week, down by 794 thousand barrels per day from the previous week.
              -Over the last four weeks, crude oil imports have averaged 9.5 million barrels per day, 500 thousand barrels per day above the same four-week period last year.
              -U.S. commercial crude oil inventories (excluding those in the Strategic Petroleum Reserve) decreased by 1.9 million barrels from the previous week.
              -At 359.9 million barrels, U.S. crude oil inventories are above the upper limit of the average range for this time of year
              -Distillate fuel inventories decreased by 0.4 million barrels, and are above the upper boundary of the average range for this time of year.
              -Total products supplied over the last four-week period has averaged 19.6 million barrels per day, up by 0.7 percent compared to the similar period last year
              -Jet fuel demand is 0.8 percent lower over the last four weeks compared to the same four- week period last year.
              -During June and July of 2010, the Gulf oil producing region was impacted by two storms: Alex and Bonnie shut in a cumulative total of about 1.6 million barrels of crude oil production.


              Patrick M. Ambrus
              Twitter: AnalyzeCapital

              Empirical data is courtesy of eia.gov

              Wednesday, September 8, 2010

              JPY Trade: Reloaded


              Morpheus: I imagine that right now, you're feeling a bit like Alice. Hmm? Tumbling down the rabbit hole?
              Neo: You could say that.

              --The Matrix


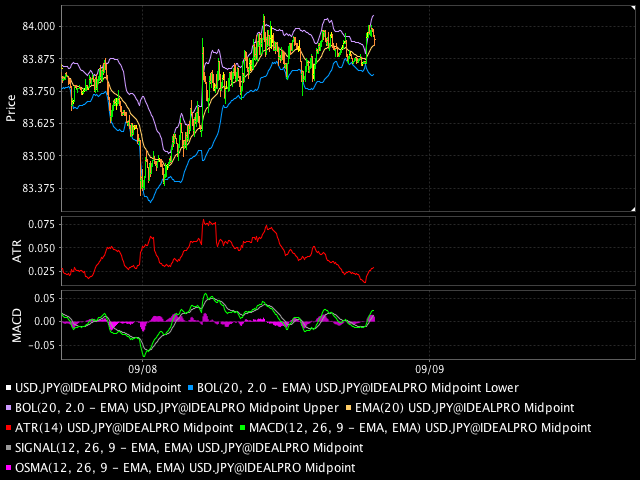
              I do feel a bit like Alice. TheUSD/JPY pair rallied in London and New York trading after selling off in Asian trading. The FX rate established a new 15-year low during the session, trading down to levels of 83.35. I took profits on the pop, during morning U.S. trading, around 84.00 levels. Prices recovered when Finance Minister Yoshihiko Noda 'said he is prepared to take “bold” steps on currencies if necessary.' However, I am contemplating a long position in the Yen until 82.50. I watched the tape for the majority of the past 48 hours (fun times) to get a feel for directionality. I am confident prices will move lower.

              Part of me wants to believe all of this intervention talk, led by PM candidate Ichiro Ozawa, will lead to more 'normalized' price levels (i.e. 88-90). However, my sinister half believes this was a short-covering rally today. In the ten minutes preceding the Beige Book announcement the pair came to an abrupt slow down in trading. Once the words 'decelerated growth' were uttered on CNBC prices gapped down to 83.79-81. During President Obama's 'Economic Speech', shortly thereafter, prices jumped back up to 83.92-95 levels. Hence, U.S. economic speak was not a significant momentum catalyst, net of direction, for the pair.


              JPY 2day chart- 5 minute bars


              Will the tape top out at 84.125 resistance levels? What has changed over the past 48 hours to stunt the momentum of a six month downtrend in the USD/JPY pair? Clearly, many uncertainties and rapid-fire change engulf trading. Thus, I look to a glut of international economic data releases that may potentially impact price directionality:

              19:50- JPY BSI Large Manufacturing Conditions
              01:00- JPY Household Confidence
              02:00- JPY Machine Tool Orders
              02:00- German CPI (MoM)
              04:30- ECB Monthly Report
              07:00- BoE Interest Rate Decision
              08:30- U.S. Trade Balance
              08:30- U.S. Initial Jobless Claims
              19:50- JPY GDP(QoQ)
              19:50 BoJ Monetary Policy Meeting Minutes


              If I have learned one thing in my short few years of trading it is, 'don't trade against the tape.' I will leave you with some wise words from Adam Smith:

              "The chance of gain by every man is more or less overvalued, and the chance of loss is by most men undervalued and by scarce any man who is in tolerable health and spirits valued more than it is worth."

              Patrick M. Ambrus
              Twitter: AnalyzeCapital

              ---------------------------
              USD/JPY = 93.9150 as of 19:37 EST. The 'Matrix' theme for this post was inspired by a fellow trader of mine, Sauros, please view his blog: http://blog.thelordoftrading.com/2010/09/welcome-back-to-real-world-neo.html. Yoshihiko Noda quote was borrowed from Bloomberg.com.

              Wednesday, September 1, 2010

              Illustrious Imperfections


              This evening I was perusing FT's Alphaville blog and came across a great piece written by Mohammed El-Erian. The PIMCO Chief Investment Officer breaks down Bernanke's speech from Jackson Hole.

              Link:http://ftalphaville.ft.com/blog/2010/08/27/328906/el-erian-how-to-read-bernanke%E2%80%99s-jackson-hole-speech/

              Some questions for the FED

              El-Erian alludes to some great points....

              1. Is the FED over-estimating its 'grip' on the U.S. economy?
              2. What happens when Treasury purchases become the new norm?
              3. How does the FED's current monetary policy measures stack up against those of other central banks (ECB, BoE, and BoJ)?
              4. The main question that trumps all, is the FED comfortable maintaining a $2 Trillion Balance Sheet over the next 10 years?
              4a. If yes, will Quantitative Easing become the new tool to re-inflate economies?

              Seems to me 'Helicopter Ben' did his homework on the lost decades in Japan.

              Patrick M. Ambrus
              Analyze Capital LLC
              Twitter: AnalyzeCapital

              Friday, August 27, 2010

              DJIA Update- Charting for Success

              Dow Jones Industrial Average Technical Analysis

              Daily Chart-6 months


              Notes:
              -Momentum still has plenty of room to fall as it just passed break-even territory
              -Resistance appears to be forming at the 50-day SMA or 10,300 level
              -We could see potential support slightly above 9900-9950
              -If this level breaks, Dow could fall to 9300-9500 range, though next clear level of support on the daily chart is 9800
              -Expect to see a retest of 50 on the RSI to confirm a downtrend if the re-test fails
              -The most recent sell-off lacked aptly confirming volume
              -Possibly a head and shoulders reversal pattern


              Weekly Chart- 2 Years


              Notes:

              -Support may come at levels of 9,600-9,700
              -200 day SMA acts as near-term resistance, this equates to a price level of 11,000
              -The last rally to 11,000+ was confirmed by robust volume
              -Momentum still has room to move to the downside, though it looks to be flattening out
              -The 50 day SMA is poised to cross the 200-day SMA, ‘The Golden Cross’, which indicates a strong bullish signal
              -35-37 will need to be broken on the RSI for this down-trend to continue

              Conclusion:

              The Daily and Weekly charts both tell equally convincing stories. The Daily chart indicates very bearish sentiment while the Weekly indicates a potential rally is on the way. Thus, in-lieu of the toss-up, I will look to volume over the next few trading days to indicate which way the tape might be headed. At this time, the Dow is up 151.90 points to 10,137.70. A short-covering rally may be underway, or the bulls may be winning the battle today. Regardless, many bears exist in the market, it is only a matter of time before market participants show their true costumes.


              Patrick M. Ambrus
              Analyze Capital LLC
              Twitter: AnalyzeCapital

              Wednesday, August 25, 2010

              Crude Oil Inventories & Commentary


              Oil is falling sharply in reaction to large builds in weekly inventory data. Oil stocks rose 4.1 million barrels with gasoline stocks up 2.3 million and distillates up 1.8 million. The data are for the August 20 week.

              Gasoline demand slowed to a 3.0 percent year-on-year pace vs. 3.5 percent and 3.3 percent in the prior weeks. Distillate demand has been slowing abruptly for nearly two months, now at plus 4.9 percent year-on-year. Supply has been heavy the past year but signs of trouble on the demand side may now begin to shift the picture for oil which has been narrowly rangebound all summer.

              Bloomberg.com


              Has Crude finally found a bottom to this downtrend? It is hard to say. To quote Alex, " 50/50 chance crude ticks up." I do concur. Supply levels of NYMEX WTI are out of control. However, as long as emerging markets demand remains robust, crude should not fall below $65/b. I need to see price movement above the $75-76 line before I turn bullish once again. For now the tape is range bound. Until supply witless down and the EUR/USD pops, I expect crude to trade between $70.50 -$74.

              In case anyone was wondering, I was stopped out of My USO calls. Extremely poor trade on my behalf. At least I learned a valuable lesson. Don't buy calls without protection. I will be trading futures for the foreseeable future.

              Related ETFs: PowerShares DB Crude Oil Dble Long ETN (DXO), UltraShort Oil & Gas ProShares (DUG), iPath S&P GSCI Crude Oil Ttl Ret Idx ETN (OIL)

              Sports: Team USA smacked Greece 87-59. Eric Gordon led the way with 18 points, 4-7 from the promise land.

              Patrick M. Ambrus
              Analyze Capital LLC
              Twitter: Analyze Capital

              Wednesday, August 18, 2010

              Gauging Market Sentiment


              The current equity market is a lethargic trade. The more I look into potential trades the more I find a lack of opportunity. Since The May 9, 2010 ‘Flash Crash’ markets adopted an elusive modus operandi. The European Sovereign Debt crisis waned in and out of news, a bubble in Gold prices tempted us, and economists argued the nuances of stimulus vs. austerity. I miss the ubiquitous uncertainty.

              Over the last 10 days volume in the SPY SPDR ETF averaged almost 190 million shares per day. In contrast, over a 3-month span, the SPY averaged close to 252 million shares changing hands daily. Thus, volume decreased by 24.6%. In addition, The GLD SPDR Gold Trust averaged only 10.3 million shares traded in the most recent 10 days. Meanwhile, GLD volume averaged 14.2 million shares per day in the most recent 3 months. Hence, volume declined by 27.5%.

              The SPY is the largest ETF by AUM with 66.8 Billion under management. StreetTracks Gold is the second largest with 51.2 Billion under control. What has cooled trading in the aforementioned derivative-like securities? For one, volume has decreased throughout equity markets for the better part of August. Though, with all the technological advances in High Frequency Trading, iPhone/BlackBerry trading apps, and trading robots, we live in an age were trading routinely flashes 24/7-365. Vacation time alone cannot explain the illustrious drop in volume.

              Let’s skin this cat another way. What market has seen a consistent uptick in volume without decline? The bond market has. The iShares Investment Grade Corporate Bonds ETF, LQD, volume rallied 13.53% over the past 10 days in comparison to the prior 3 months. Additionally, the iShares TIPS Bond ETF, TIP, saw volume increase by 5.23% over the past 10 days in comparison to average 3-month volume. Now don’t let me get carried away with these statistical redundancies. Empirical reason suggests a normalcy in the gradual volume changes. Spreads continue to tighten as interest rates remain at near zero levels and inflation subsides. Yet, I’m not convinced investment grade debt is the correct safe haven.

              Aside from bond prices and yield curves, what catalysts chauffeur equity prices? U.S. economic data often sits behind the wheel. Central Bankers remain the biggest elephants in the room, in particular the FED. The FOMC has found a way to implement a new Quantitative Easing program without calling it QE. The Fed will take proceeds from its MBS securities and buy U.S. Treasury Notes. Hence, U.S. notes continue to yield near-all-time-low interest rates. One thing the FED is clear on, the committee fears deflation. Thus, the committee led by Helicopter Ben will continue to shower the economy with liquidity. Until the day of reckoning comes, expect investment grade debt to rally. I also expect corporate debt issuance to exacerbate demand.

              Remarkably, I managed to construct a top down argument that bottoms up. The FED’s decision making on monetary policy and QE will affect the bond market, which will drive equity prices. I surmise, global debt markets coalesced to form a bubble. Now that we know a bubble exists, we need to know how large it will grow and when it will pop. Although calling a top or bottom is dangerous, pointing out a bubble is reasonable and needs recognition. Undoubtedly, equities will benefit tremendously from the unwinding of the crowded debt trade. My suggestion is to short overbought bond ETFs and long growth/value equity ETFs. This may be a defensive play, but it will work in time.

              Bond ETFs: iShares TIPS Bond Fund (TIP), , iBoxx $ Investment Grade Corporate Bond Fund (LQD), Vanguard Total Bond Market ETF (BND)

              Equity ETFs: Russell 1000 Growth Index Fund(IWF), Vanguard Total Stock Market ETF (VTI), ELEMENTS Benjamin Graham Large Cap Value ETN


              Patrick M. Ambrus
              Analyze Capital LLC
              Twitter: Analyze Capital

              Monday, August 16, 2010

              Japan GDP Growth


              The Gross Domestic Product (GDP) in Japan expanded at an annual rate of 5.00 percent in the last quarter. Japan Gross Domestic Product is worth 5068 billion dollars or 8.17% of the world economy, according to the World Bank. Japan's industrialized, free market economy is the second-largest in the world. Its economy is highly efficient and competitive in areas linked to international trade, but productivity is far lower in protected areas such as agriculture, distribution, and services. Japan's reservoir of industrial leadership and technicians, well-educated and industrious work force, high savings and investment rates, and intensive promotion of industrial development and foreign trade produced a mature industrial economy. Japan has few natural resources, and trade helps it earn the foreign exchange needed to purchase raw materials for its economy. This page includes: Japan GDP Growth Rate chart, historical data and news.

              tradingeconomics.com

              Export oriented growth remains resilient. However, The world's second largest economy faces a grave test of fiscal fat camp. The island's budget deficit as a percent of GDP staggers at -7.5%. Also, political reform/turnover transcends any progress made from previous fiscal reform.

              Alas not all hope is lost. Deflation fears begin to subside while unemployment holds around 5%. Additionally, Industrial production surged 17.0% from June 2009. Now, Japan's leadership needs to make lemonade. Naoto Kan a former finance minister and current PM, may be the correct leader to tame the ravenous debt beast as well as exploit the island's strengths.


              Patrick M. Ambrus
              Analyze Capital LLC
              Twitter: Analyze Capital

              Tuesday, August 10, 2010

              FOMC Decision


              Information received since the Federal Open Market Committee met in June indicates that the pace of recovery in output and employment has slowed in recent months. Household spending is increasing gradually, but remains constrained by high unemployment, modest income growth, lower housing wealth, and tight credit. Business spending on equipment and software is rising; however, investment in nonresidential structures continues to be weak and employers remain reluctant to add to payrolls. Housing starts remain at a depressed level. Bank lending has continued to contract. Nonetheless, the Committee anticipates a gradual return to higher levels of resource utilization in a context of price stability, although the pace of economic recovery is likely to be more modest in the near term than had been anticipated.

              To help support the economic recovery in a context of price stability, the Committee will keep constant the Federal Reserve's holdings of securities at their current level by reinvesting principal payments from agency debt and agency mortgage-backed securities in longer-term Treasury securities. The Committee will continue to roll over the Federal Reserve's holdings of Treasury securities as they mature

              federalreserve.gov


              Thomas M. Hoening was again the lone FOMC dissenter. Since Helicopter Ben uttered the phrase 'nascent recovery' on Capital Hill, cryptic language has proceeded. Clarity from the FED going into the 4th quarter is unquestionably salient. Perhaps, we (market participants) should sit tight until Jackson Hole concludes. Surely, transparency will become abundantly apparent after the curtains close at the Committee's annual Wyoming refuge.

              Uncertainty is apparent in risk/reward security markets. At this point in time, The FED maintains relevance and reverence on the Streets plastered with Investment Banks rather than cafe's and bakeries. Ergo, Monetary Policy must remain stable as U.S. fiscal policy shifts political party lines. The Bush tax cuts abide while politicians play musical chairs.

              Something tells me Precious and Industrial metals may be the best play in the 4th quarter as risk aversion reigns supreme. Unless of coarse one likes Government Debt.

              Related ETF's: iShares Barclays 10-20 Year Treasury Bond Fund (TLH:US), GS Connect S&P GSCI Enhanced Commodity Total Return Strategy Index ETN (GSC:US), ETFS Palladium Trust (PALL:US), E-TRACS UBS Long Platinum ETN (PTM:US)

              Literature: Karl R. Popper's The Open Society and Its Enemies 2 Hegel and Marx

              Sports: T-Mac finally gets another shot. Former Superstar Tracey McGrady officially Signed with the Detroit Pistons today. Detroit's backcourt is crowded.

              Patrick M. Ambrus
              Analyze Capital LLC
              Twitter: Analyze Capital
               
              Disclaimer
              This Blog has been developed by Analyze Capital LLC, and as an independent organization we provide “AS IS” information without warranty. The ideas and opinions expressed by the contributers of this blog are personal and do not represent the actions or policies of Analyze Capital LLC. The contents of this blog do not intend to assert recommendations or to offer advice of any kind. We are not responsible the consequences, be they gains or losses, that may result from using any of the information from this blog.